Think You Need a Huge Down Payment to Buy a House? Let’s Run the Numbers.
One of the biggest misconceptions I hear from buyers is that you need a giant pile of cash sitting in the bank before you can even think about buying a home.
You do need money. Unfortunately, nobody has figured out how to make that part disappear yet.
But the amount you actually need out of pocket may be a lot less than you think, especially when the offer is structured strategically.
Let’s use a $375,000 home purchase as an example.
The Scenario
Let’s say you’re using an FHA loan, putting 5% down, and your interest rate is around 6.9%.
Your 5% down payment would be:
$18,750
Your base loan amount would be approximately $356,250.
FHA loans also have an upfront mortgage insurance premium, which can generally be financed into the loan rather than paid entirely out of pocket at closing.
So far, pretty straightforward.
But here’s where the offer itself can make a big difference.
What If We Ask the Seller to Help With Closing Costs?
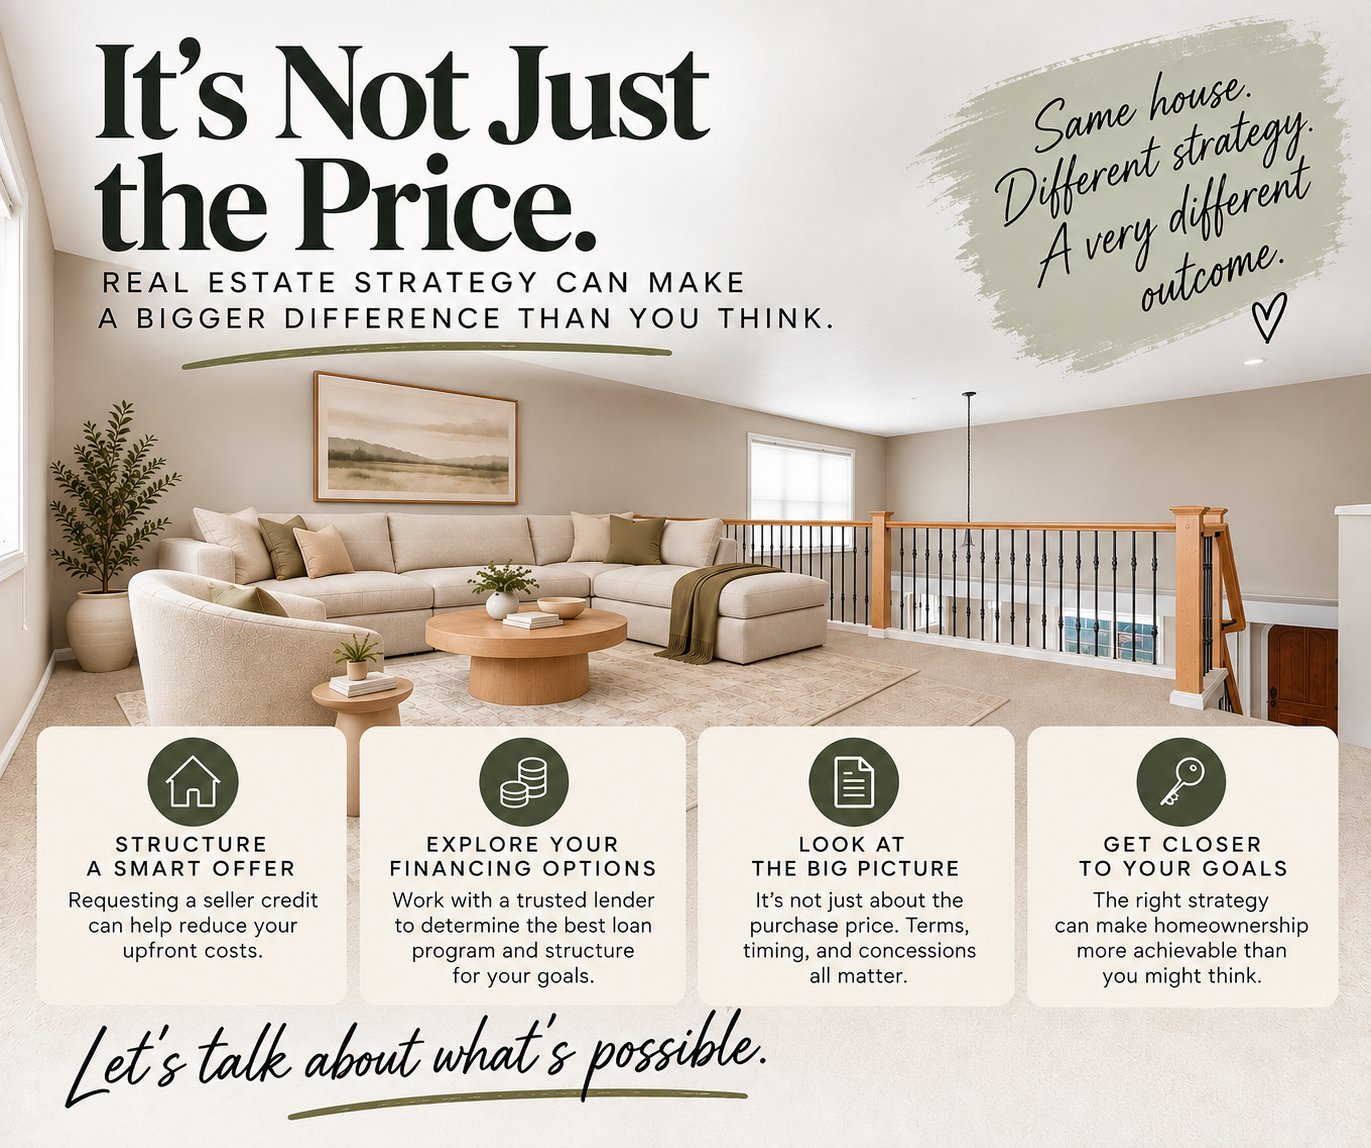
In this example, let's say we write the offer requesting a 3% seller credit toward the buyer's allowable closing costs and prepaid expenses (each loan type have their own set of rules for allowable credits).
On a $375,000 purchase, 3% equals:
$11,250
That credit could potentially be used toward eligible expenses such as lender fees, title and escrow charges, prepaid property taxes, homeowners insurance, discount points, and other allowable costs associated with the loan.
It does not mean the seller hands you an $11,250 check at closing. Nice try.
The credit has to be used for costs permitted under the loan and transaction.
So What Could the Buyer Actually Need?
The buyer's 5% down payment is:
$18,750
Normally, the buyer would also need additional money for closing costs and prepaid expenses. Those amounts vary depending on the lender, property taxes, insurance, closing date, loan terms, and the specific property.
But in this example, we have up to $11,250 in seller-paid closing costs available.
If the buyer has enough eligible closing costs and prepaid expenses to use the full credit, that $11,250 can substantially reduce the amount of additional cash they need to bring to closing.
So instead of automatically assuming you need your down payment plus another giant pile of money for closing costs, your actual cash requirement could potentially be much closer to the down payment itself.
And if you've already deposited earnest money, that money is credited toward the funds you need at closing.
What About the Monthly Payment?
Using our example of a $375,000 purchase, 5% down, FHA financing and an interest rate around 6.9%, principal and interest would be roughly $2,390 per month after financing the FHA upfront mortgage insurance premium.
FHA monthly mortgage insurance would also apply, along with property taxes and homeowners insurance.
So no, the total payment isn't $2,390. I wish.
Your lender will calculate the actual payment based on the property, insurance, taxes, interest rate, mortgage insurance, and your final loan terms.
Could We Use Some of the Seller Credit to Lower the Interest Rate?
Potentially, yes.
If the buyer doesn't need the entire seller credit for other eligible closing costs, some of the available credit may be usable toward discount points to reduce the interest rate.
This is also why choosing the right lender matters.
A good lender shouldn't just tell you whether you qualify. They should help you understand your options, compare different loan structures, explain what those choices mean for both your upfront costs and monthly payment, and help you decide what makes the most sense for you.
There isn't one financing strategy that's automatically best for every buyer.
If you already have a lender you trust who is taking the time to walk you through those options, great. If you don't, or you feel like you're getting numbers thrown at you without much explanation, I can refer you to trusted lenders who will help you understand your options and make the choice that's right for you.
The Bigger Point
Buying a house isn't just about finding one you like and throwing a number at the seller.
How the offer is structured matters.
On the exact same $375,000 house, one buyer might assume they need the down payment plus thousands more for closing costs.
Another buyer may structure an offer requesting a seller credit that significantly reduces those additional upfront expenses.
Of course, the seller has to agree to the credit. The buyer has to qualify for the financing. The property has to qualify. And the lender ultimately determines which costs the credit can be applied toward.
But that's exactly why it's worth running the numbers before deciding you're not ready.
If you've been sitting on the sidelines because you assume you need $30,000, $40,000 or more in cash before you're allowed to start looking at houses, let's actually run the numbers first.
You might be closer than you think.
I am not a lender. This example is for educational purposes only and is not a loan estimate or guarantee of financing. Interest rates, FHA requirements, mortgage insurance, allowable seller contributions, closing costs, taxes, insurance and qualification requirements can change and vary by borrower and transaction. Buyers should confirm financing terms and allowable credits with their licensed mortgage professional.